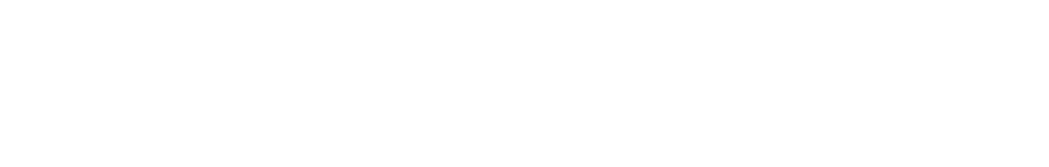

Lucerne has reduced its effective tax burden on businesses from 11.91 per cent to 11.66 per cent compared with the previous year. Zug also reduced its rate, from 11.85 per cent to 11.71 per cent, but was unable to retain its top position. The lead is small. Nevertheless, its impact on competition between business locations could be significant.
For businesses, taxes are more than just a figure in the annual accounts. They influence decisions on where to locate, investments, expansion and, consequently, where jobs are created. Lucerne is sending a clear message. The canton aims to score points not only with its scenery and quality of life, but also with competitive financial conditions.
The contrast within Switzerland remains striking. In Bern, the combined effective corporation tax rate is 20.54 per cent, whilst in Zurich it is 19.47 per cent. Lucerne is thus significantly lower than the major economic centres and tops the list of tax-friendly locations in Central Switzerland.
The second tax landscape
The PwC comparison shows ordinary corporation tax rates. The effects of the OECD/G20 minimum tax on large corporate groups are not reflected in this comparison. Corporate groups with an annual turnover of at least 750 million euros must achieve an effective minimum tax rate of 15 per cent in each tax jurisdiction.
In the canton of Lucerne, this affects an estimated 220 companies. For these groups, the advantage of the standard rate of 11.66 per cent is largely offset by the minimum tax. For companies outside the scope of the measure, however, the low standard profit tax burden – depending on the municipality – remains a significant locational advantage.
Higher taxes to boost the region’s appeal
The Cantonal Council has approved a package of measures for the further development of the canton as a place to live and do business, totalling 250 million Swiss francs for the year 2026. Just under two-thirds of the funds are earmarked for business-related measures.
At the heart of this is the Lucerne Innovation Grant. With around 110 million Swiss francs earmarked for 2026, it is the most significant individual measure. Companies with an actual economic presence in the canton can use it to fund research, innovation and development projects, subject to clear conditions. Eligible for support are, amongst other things, staff costs in research and development, investments, contract research and other expenses. This is shifting the dynamics of competition between business locations. Low taxes remain important. However, for large firms, support, skilled workers, research, available space and efficient infrastructure are becoming increasingly decisive factors.
Competition is becoming more demanding
The municipalities are also at the table. The 2027 tax law revision is intended to redefine the municipalities’ share of revenue from the minimum tax. The plan is to allocate 25 per cent of the additional revenue, with a minimum of 26.6 million Swiss francs annually until 2029 and at least 23.5 million Swiss francs thereafter. This raises the political question of how the additional tax revenue will be distributed between the canton and the local authorities, and how much of it will be channelled into promoting innovation, enhancing the quality of the business environment and funding public services.
Lucerne has narrowly overtaken Zug in the tax comparison. But the top spot in the tax rankings is not the end goal. Whether this new leading position translates into lasting strength as a business location will not be determined by the 11.66 per cent figure alone. What matters is how Lucerne utilises its new financial leeway.
Lucerne dethrones Zug
More Articles
Commercial sites in Zurich are being converted into housing
In the canton of Zurich, more than 20,000 additional flats could be built on existing industrial and commercial sites. The new study comes at a time when the market remains…
Amendments to the Anti-Money Laundering Act introduce new obligations for estate agents, even where no money changes hands
Since 1 October 2026, stricter anti-money laundering regulations have been in force for the Swiss property sector. Under the new rules, estate agents, trustees and other professionals may now also…
Risk of a bubble falls, but price pressure remains
The Swiss housing market took a brief breather in the third quarter of 2026. The UBS Swiss Real Estate Bubble Index fell by 0.07 to 0.64 points. However, there is…
Zurich is fighting back against falling vacancy rates
Across Switzerland, the vacancy rate continues to fall below the 1 per cent mark. However, the picture for rental flats varies from region to region. Whilst the number of vacant…
From M-Parc to Bauhaus: Langenthal gets a new business park
The DIY chain Bauhaus is set to open its eighth specialist centre in Switzerland on 5 March 2027 at 17 Murgenthalstrasse.