
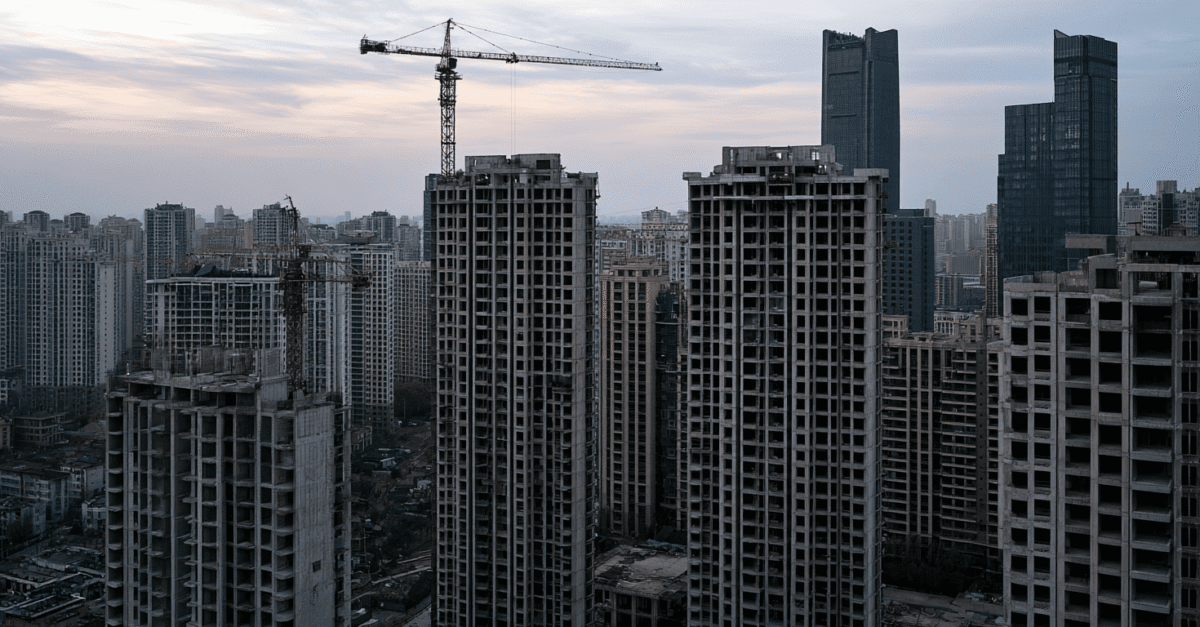
This change strikes at the heart of the old model. The three relevant ministries – Housing, Natural Resources and Financial Supervision – now require that the load-bearing structure of each individual building be completed before new pre-sale projects can go ahead. At the same time, advance payments and private mortgages must be held in full in supervised accounts until a project has been approved and the conditions for handover have been met.
The new regulations do not apply retroactively across the board to ongoing projects. The regulations of 28 August 2026 allow projects that had already been granted planning permission before they came into force to continue under the previous guidelines. The change is therefore primarily aimed at new residential projects and at a gradual shift away from the traditional pre-sale model.
Pre-sales lose their financing role
As a result, pre-sales lose a large part of their previous function as a cheap form of interim financing. In China, buyers’ funds have been used for years to support construction progress, land purchases and, in some cases, existing liabilities. In future, projects are to be pre-financed to a greater extent using own funds, bank loans or capital market financing. This shifts the risk from buyers back to developers and lenders.
Market data shows just how delicate this transition is proving to be. According to the Chinese National Bureau of Statistics, investment in property development fell by 19.9 per cent between January and August 2026. Sales of new flats and other new residential properties fell by 12.1 per cent in terms of floor area, whilst developers’ cash inflows plummeted by 21.0 per cent. Of particular significance is the 14.8 per cent decline in deposits and advance payments, as well as the 22.4 per cent fall in private mortgage loans.
Pressure on private developers continues to mount
Private developers in particular are thus losing their most important source of liquidity in a market that is already parched. State-affiliated groups have clear advantages when it comes to accessing finance and are likely to take over market share if weaker providers are forced to sell off projects or building land. This is also a cause for concern for local authorities, as fewer new projects and more cautious developers could put further strain on revenue from land sales.
For banks, this drastic measure is a mixed blessing. Greater fiduciary protection can bolster buyer confidence and reduce the risk of unfinished flats. At the same time, the new system forces developers to rely more frequently on bank loans, even though the sector is already suffering from falling sales, weak collateral and high refinancing pressure. Beijing is thus banking on a structural overhaul of the housing market, but accepts that the consolidation process will be even more painful in the short term for developers, lenders and local finances.